Los Angeles CPA for Real Estate Investors
1031 without the scramble.
1031 timeline control, cost segregation, appeals, and S-Corp salary that holds up under exam.
Important Upcoming Dates
Stay ahead of critical federal and California tax deadlines. Mark your calendar or reach out to schedule a planning session ahead of each date.
Extension Filing Deadline
Extended Form 1040 and CA Form 540 returns due
CA Property Tax Appeal Deadline
Assessment Appeals Board filing window closes (Los Angeles County)
Q4 Estimated Tax Payment
Federal and CA Form 540-ES Q4 installment due
S-Corp & Partnership Deadline
Form 1120-S / 1065 and CA Form 100S / 565 due
Seven practice areas. One firm.
Each area connects to the others — so your returns, your deals, and your exit plan line up.
Tax & Accounting
Full-ServiceEvery return. Every strategy. Every entity.
Comprehensive tax planning, preparation, and filing across all entity types — from individuals and partnerships to complex real estate structures and multi-state operations.
1031 Exchanges
Like-KindThe 45-day clock, under control.
A 1031 exchange with the 45-day clock under control — identification, the intermediary, DST and TIC, reverse and improvement deals.
Real Estate Tax
Full-Cycle OptimizationAcquisition to exit, optimized.
Entity choice at purchase, a cost segregation study when it pays, depreciation at hold, and the exit planned before you list.
OBBBA
One Big Beautiful Bill ActPlan for the law in front of you.
The One Big Beautiful Bill Act (OBBBA) — signed 2025 — permanently extends bonus depreciation, modifies SALT, and expands QBI deductions. We reposition your structure to capture what the current code allows.
Property Tax Appeals
Assessment ChallengesChallenge unsupported assessments with evidence.
Assessments can exceed supportable market value. Our systematic appeal process leverages market data, comparable analysis, and administrative expertise to pursue a reduction.
AI Consulting
Where it helpsWhere it actually saves time.
Help using automation on tax and planning work where it actually saves time.
Virtual CFO
Embedded StrategyCFO-level strategy. Without the overhead.
We act as your embedded CFO year-round — driving financial strategy, scenario modeling, and investor reporting without the cost of a full-time hire.
Real estate tax questions,
answered in plain English.
Select a topic
Select a topic for your intelligence brief
AI-generated responses are for general information and do not constitute tax, legal, or accounting advice. Consult a qualified CPA before acting on anything here.
News & Insights
Tax law moves fast. Stay ahead.
Use REPS to Deduct Real Estate Losses from Your Income
Turn your passive rental losses into tax savings by qualifying for Real Estate Professional Status. We explain the requirements, the spousal strategy, and how to avoid audit triggers.
Keep Your Low California Property Taxes When Transferring Real Estate to an LLC
Learn how to move your property into an LLC without triggering a costly reassessment. Use these specific rules to protect your Prop 13 tax savings.
Sep 20, 2026 · 2 minUse Short-Term Rentals to Reduce Your 2026 Tax Bill
Offset your ordinary income by using short-term rental losses. Skip the Real Estate Professional Status requirements by following these simple tax rules.
Sep 6, 2026 · 2 minExit Real Estate Partnerships and Defer Taxes Using Swap-and-Drop
Keep more profit and resolve partner disagreements by using the swap-and-drop method. This strategy helps you separate individual goals using §1031 and §731.
Aug 30, 2026 · 9 minA Real 1031 Exchange Timeline for 2026 (What LA Investors Get Wrong)
The 45-day and 180-day clocks, boot, depreciation recapture, and DSTs. How a Los Angeles CPA actually walks a client through a 1031 exchange in 2026.
Aug 23, 2026 · 2 minCalifornia Doesn't Follow the IRS on Bonus Depreciation
The IRS lets you write off most of a cost-seg asset in year one. The FTB does not. What that split costs you in recordkeeping, basis, and the year you sell.
Aug 18, 2026 · 2 minResults that
speak for themselves.
LaviCPA identified a $340,000 assessed-value reduction on our industrial portfolio. At the local tax rate, that translated to approximately $47,200 in annual property tax savings. The appeal process was seamless — we didn't attend a single hearing.
Outcomes vary based on individual facts. These examples are illustrative and do not guarantee results.
CFO-level strategy.
Without the overhead.
Every engagement begins with a complimentary evaluation to understand your financial architecture. We then act as your embedded CFO — driving strategy, not just compliance.
Common focus areas we address from day one:
- Financial Strategy & Long-Range Planning
- Budgeting, Forecasting & Scenario Modeling
- Cash Flow Management & Optimization
- Financial Reporting & KPI Dashboards
- Capital Structure & Debt Advisory
- Entity Structuring for Tax Efficiency
- Investor Reporting & Board Presentations
Built for investors
who think in decades.
We work with real estate developers, syndicators, family offices, and portfolio holders — people whose tax position is too involved for a generalist and too important to leave until April.
Each area of the practice connects to the others, so the return, the deal, and the exit plan line up.
Plan first. Returns that hold up — not year-end paperwork.
Every engagement begins with the exit in mind and works backward.
Cost segregation, 1031 timelines, assessment appeals, and S-Corp salary reviewed against the code and the case law.
Every recommendation is reviewed against the code, the case law, and your actual numbers — not a template. If a strategy does not hold up on examination, we do not recommend it.
You work with Elias.
Not a call center.
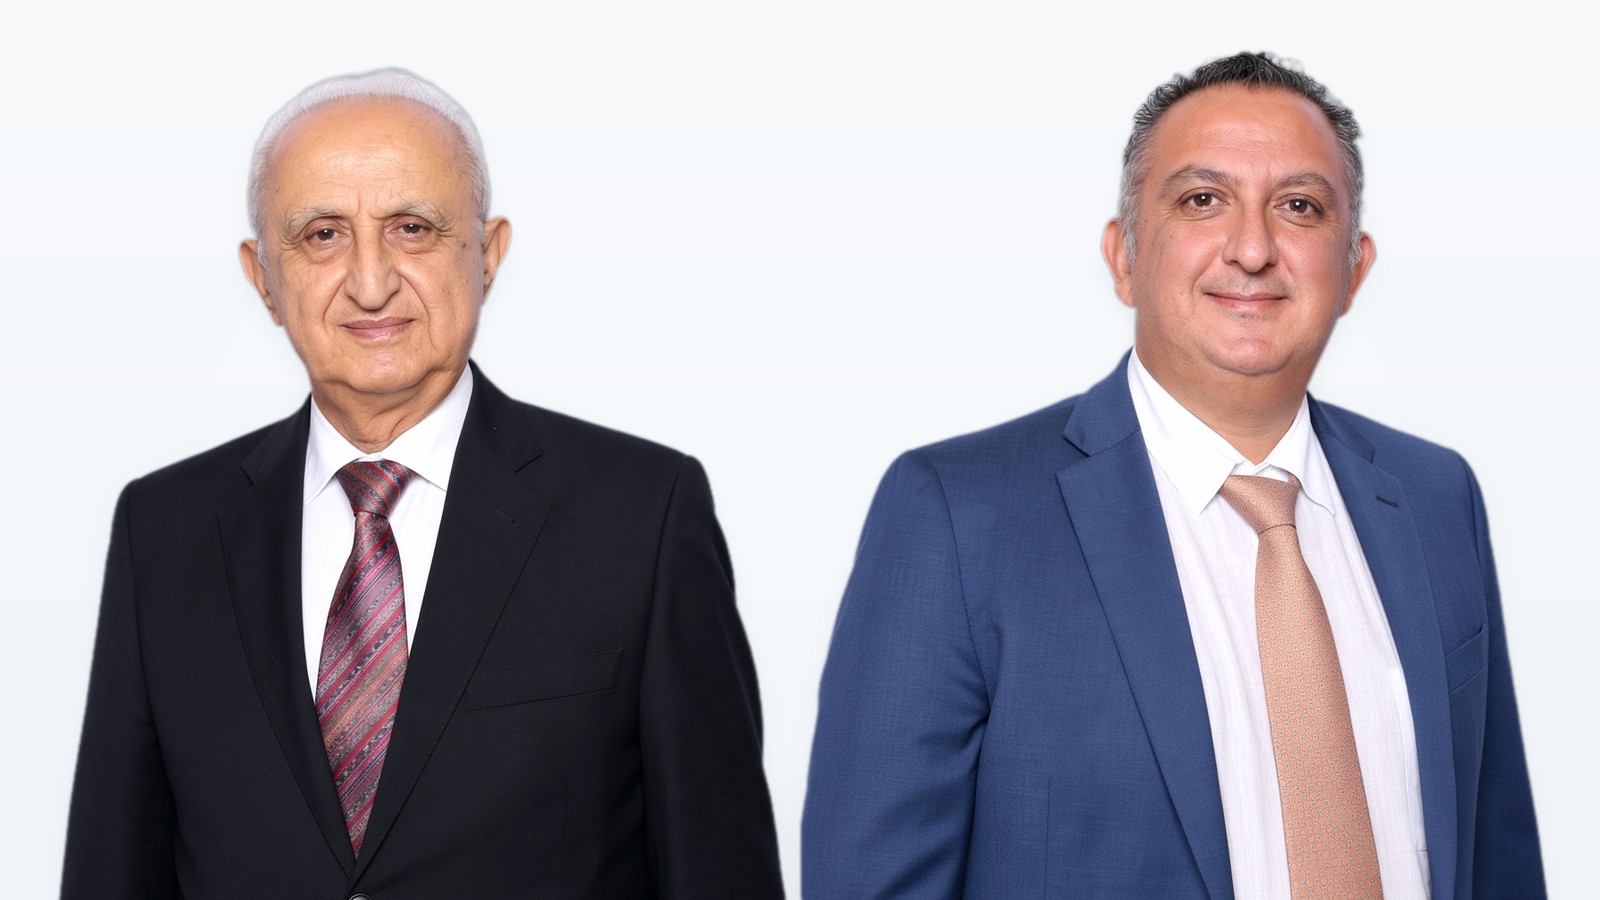
Elias Lavi began as a chartered accountant in England. He is a licensed California CPA and the principal of LaviCPA, with more than 40 years building the Los Angeles practice. No account managers, no hand-offs — if the question is your 1031 window or your cost seg study, you call Elias.
His son Shawn works alongside him as co-owner and partner.
In one multifamily engagement, a third-party cost-segregation study reclassified approximately $900,000 of eligible basis. Based on that client's federal tax profile and ability to use the resulting deductions, the implementation produced an estimated current-year federal tax benefit of approximately $315,000. California depreciation was tracked separately. Results vary based on property basis, placed-in-service date, tax rate, participation, and other limitations.
The first conversation
is always without obligation.
Complimentary 30-minute consult. We take a limited number of investors each year — we will tell you if the fit is right.