Update (September 2026): The Section 30C credit expired on June 30, 2026. Property placed in service after that date does not qualify. The article below is retained for reference and for projects that placed property in service before the deadline.

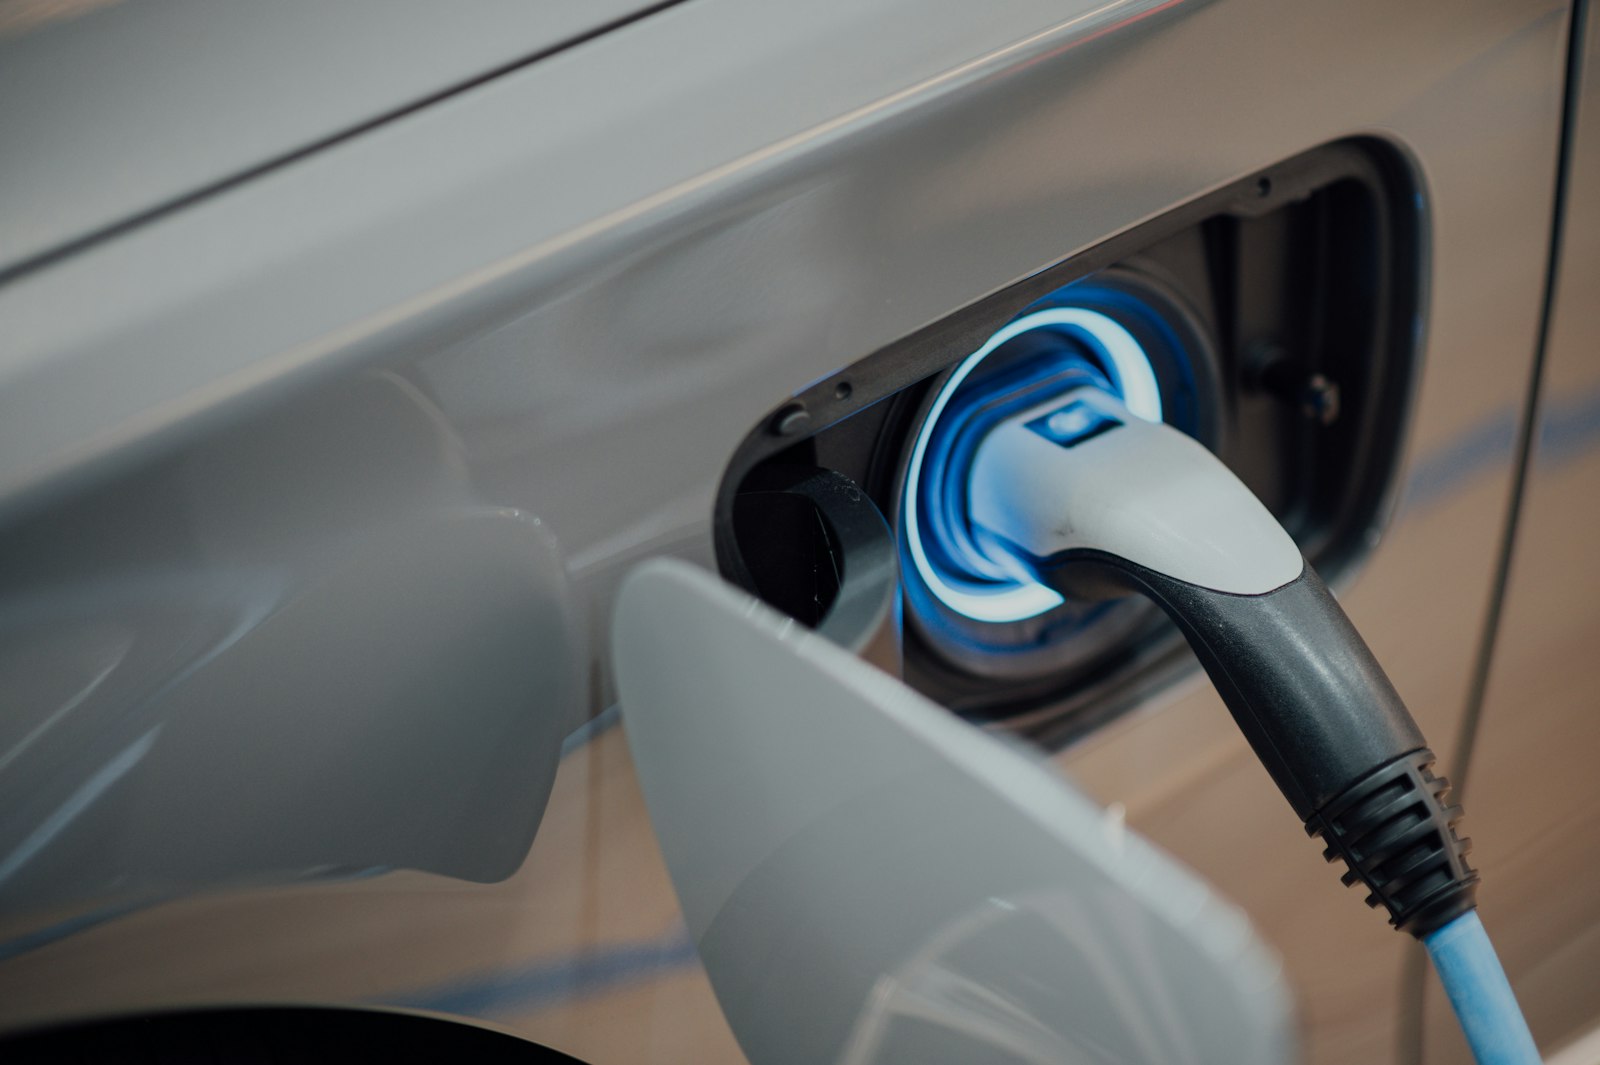
For a Los Angeles property owner, an EV charging project can raise tax, construction, and scheduling questions at the same time. The federal Alternative Fuel Vehicle Refueling Property Credit under Section 30C is tied to the date eligible property is placed in service. The credit ended for property placed in service after June 30, 2026, so the question now is whether your equipment was ready and available for use by that date.
What Section 30C Covers
Section 30C can apply to qualified equipment used to recharge electric vehicles or store or dispense qualifying clean-burning fuel. For business or investment use, the property generally must be depreciable, used primarily in the United States, and installed in a qualifying location. The credit is not an automatic rebate at the charger or equipment counter. The project, location, tax use, and records all matter.
The location test is easy to overlook. The property must be in an eligible low-income or non-urban census tract under the rules that apply to its placed-in-service date. For property placed in service after January 1, 2025, the IRS directs taxpayers to use the 2020 Census Tract Identifier when checking the location.
The June 30, 2026 End Date
The IRS currently describes the credit for qualified property placed in service from January 1, 2023, through June 30, 2026. The One, Big, Beautiful Bill Act changed the end date for Section 30C property. Property placed in service after June 30, 2026, does not qualify under the current federal credit rules.
Placed in service generally means the equipment is ready and available for its intended use, not merely ordered, delivered, paid for, or included in a construction schedule. A contract signature or a deposit by itself does not establish the placed-in-service date. Your facts and the IRS instructions control, so do not treat June 30 as a promise that an unfinished installation will qualify.
Who May Qualify
Business and investment users, including owners or operators of commercial, multifamily, office, retail, and hospitality property, may qualify when the property and location requirements are met. A tenant or business operator may need to coordinate with the property owner over ownership, depreciation, and installation records.
Individuals may qualify for qualifying property installed at a main home. Eligible tax-exempt and government entities may also use elective pay, subject to the applicable rules. These categories are not interchangeable, and the credit calculation differs between personal and business use.
How The Credit Amount Works
For business or organization property placed in service through June 30, 2026, the IRS describes a 6% credit of cost, limited to $100,000 per item. A business or organization that satisfies the prevailing wage and apprenticeship requirements may be eligible for a 30% credit with the same $100,000 per-item limit. For personal-use property at a main home, the IRS describes a 30% credit with a $1,000 per-item maximum.
The per-item rule matters. The IRS identifies each charging port, fuel dispenser, or storage property as an item for the applicable limit. Do not assume that a project-wide budget automatically produces a project-wide credit, and do not claim the higher business rate without confirming the wage and apprenticeship requirements.
Steps To Document Eligibility
- Check the tract. Use the IRS location guidance and the appropriate census-tract identifier for the placed-in-service year. Save the search result and the property address used.
- Establish the date. Keep commissioning reports, inspection sign-offs, utility or interconnection records, invoices, and contemporaneous photos showing when the equipment was ready and available for use.
- Confirm the tax use. Retain the lease, ownership, depreciation, and allocation records needed to show whether the property is business, investment, or personal-use property.
- Preserve project support. Keep equipment specifications, contractor invoices, and, if claiming the higher business rate, prevailing-wage and apprenticeship records.
- Coordinate the filing. Form 8911 and the general business credit rules may apply, depending on the taxpayer. Review the current form instructions before filing.
A Practical Example
Assume a business installs four charging ports at $25,000 each and every port is otherwise eligible. At the 6% business rate, the preliminary calculation is $1,500 per port, or $6,000 total. If the business meets the prevailing wage and apprenticeship requirements, the preliminary 30% calculation is $7,500 per port, or $30,000 total. Those figures are illustrations, not a conclusion that the project qualifies; location, placed-in-service timing, tax limitations, and the current forms still need to be checked.
What To Do Now
If your equipment was placed in service by June 30, 2026, gather the commissioning report, the inspection sign-off, and the census tract check before your 2026 return is prepared, and claim the credit on Form 8911. If it wasn't ready by then, Section 30C isn't available, and the cost is recovered through regular depreciation instead.
If you are evaluating an EV charging installation, LaviCPA can help you organize the placed-in-service evidence, location review, and tax-return coordination before you rely on the credit. Bring the project scope, address, ownership structure, and construction schedule to a consultation.
This article is for educational purposes only and is not tax, legal, or accounting advice. Credit eligibility depends on the taxpayer's facts, the property, the location, and current IRS guidance.